
Electronic health records in life insurance: trace what the data says and where it came from
Electronic health information can shorten evidence collection, but a coded item or extracted field may not contain the clinical context of a complete chart. Applicants should answer from their own history, review records when needed and use the provider's amendment process for suspected errors.
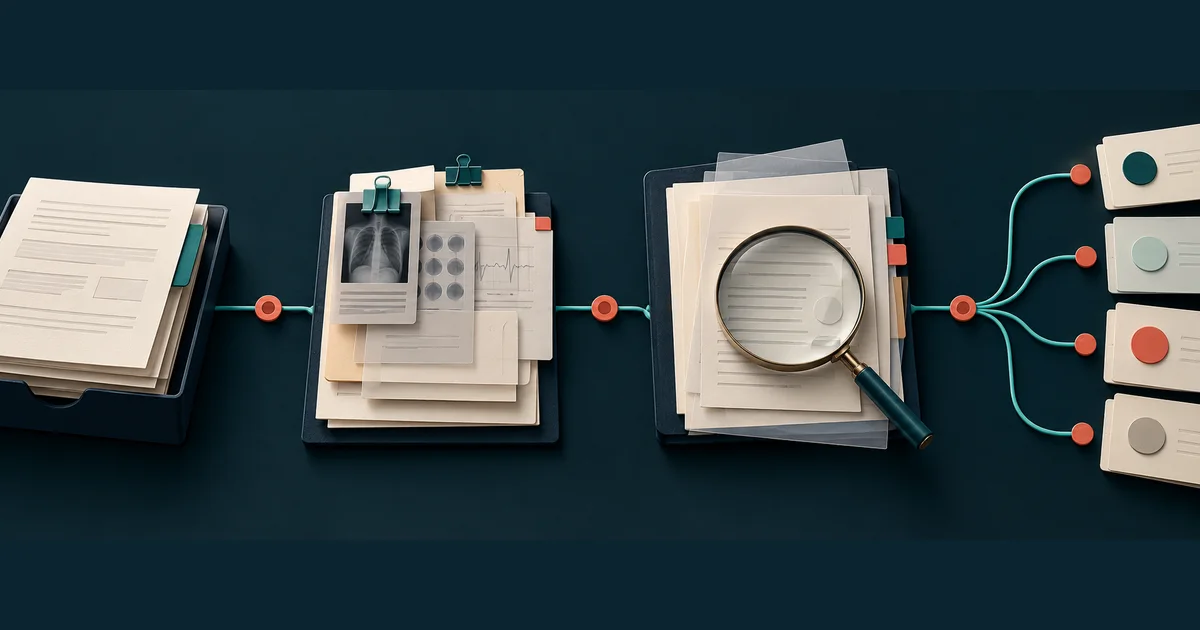
A data-provenance map for distinguishing a coded summary, prescription history, laboratory result and clinician's complete chart.
Ask what kind of electronic evidence you are seeing
“Electronic health record” can refer to a provider's chart, a patient-portal view, an exchanged summary or selected data supplied through an authorized service. A medication code, diagnosis entry, laboratory result and narrative clinician note carry different context.
Source
Which provider, facility, pharmacy or data service created or supplied the item?
Date
Is it a service date, entry date, prescription date or later update?
Meaning
Does the record show an order, result, problem-list code or clinician assessment?
Status
Is the information active, historical, corrected, canceled or still under review?
A code may need the note around it
A problem-list entry can persist after a rule-out evaluation or after a condition has resolved. A prescription record can show that medicine was dispensed, not why it was prescribed or whether it was taken. A lab value requires units, reference range and clinical setting. None should be ignored, but each should be interpreted through its source record.
Answer application questions truthfully from known history. Do not wait for an insurer to discover an inconsistency. If an answer changes after reviewing the chart, contact the agent or insurer in writing and retain the correction.
Use access and amendment rights deliberately
HHS explains that HIPAA generally gives individuals access to protected health information in a designated record set, subject to exceptions. Request the portion needed, note the covered dates and ask about format and fees. A portal snapshot may not be the complete designated record set.
If information is inaccurate or incomplete, submit a written amendment request to the provider. The provider may accept or deny it under the applicable process and may append statements rather than erase history. Preserve the request and response.
Data mismatch triage
| Mismatch | Best source | Action |
|---|---|---|
| Wrong patient | Identity and encounter records | Urgent provider correction |
| Old active status | Current clinician note | Amendment request |
| Missing context | Full report or narrative | Supply complete record |
| Wrong application answer | Submitted application | Written insurer update |
Control the application copy
See how authorization scope works, then use the records guide to understand other evidence sources. Keep the completed application and all amendments together.
Questions about electronic health records
Can I see my medical record before applying?
HIPAA generally gives individuals a right to inspect or receive copies of protected health information in a designated record set, subject to limited exceptions.
Does correcting a chart erase the original entry?
Not necessarily. A provider may accept an amendment or append a response, while retaining record history. Follow the provider's formal process and keep the response.
Primary sources and scope
Federal sources explain health-record rights. Insurance authorization and state rules may add requirements.