
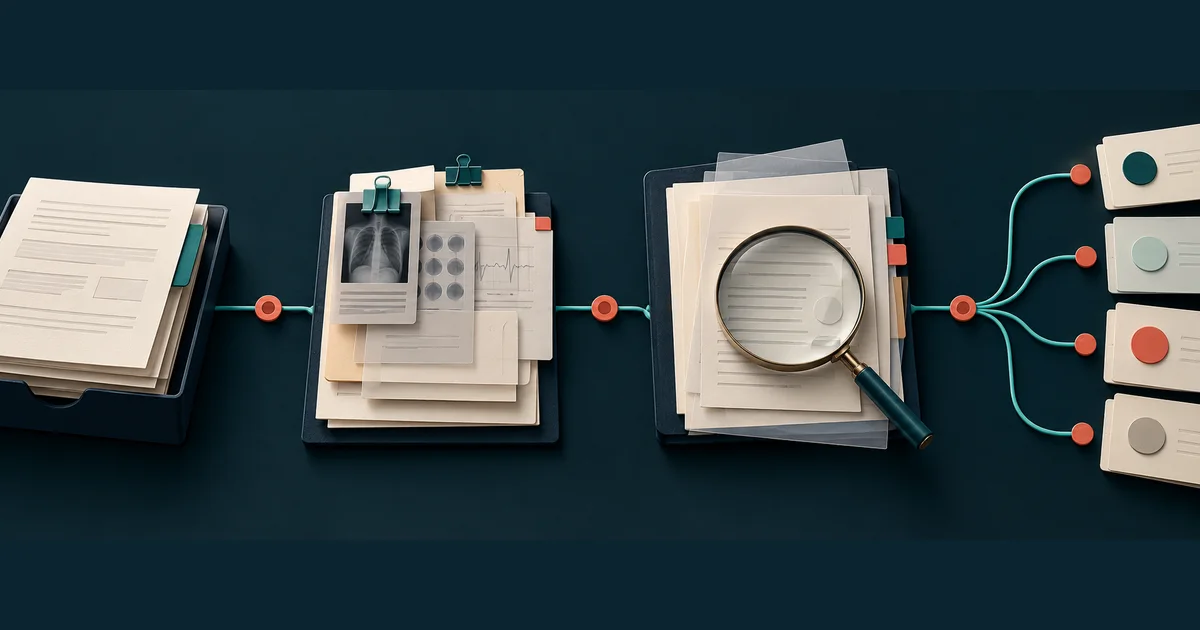
Five steps in a life-insurance review
1. The applicant asks for coverage
The request names the coverage amount, policy type and people involved. The application also asks about health, work, habits, travel and finances.
2. The insurer gathers evidence
The insurer may use the application, an interview, prescription history, medical records, lab results or a focused questionnaire. The exact mix depends on the case and local rules.
3. The underwriter checks consistency
The underwriter compares each answer with the available records. A mismatch often creates a question. It does not always mean that an answer was dishonest.
4. The insurer measures the risk
The underwriter applies that insurer's current guide. The review may consider timing, control, severity, duties, frequency and future plans.
5. The insurer gives an outcome
The insurer may make an offer, ask for more evidence, wait for a clearer pattern or decline the case. The applicant can then review the actual policy terms.
Traditional, accelerated, simplified, and guaranteed-issue underwriting
“No medical exam” does not always mean “no underwriting.” The route describes how an insurer gathers and evaluates information. Product names, eligibility rules, coverage limits, and prices vary, so read the insurer's description rather than relying on the label alone.
Traditional underwriting
The insurer may use a detailed application, medical records, an exam, and blood, urine, or saliva testing. A person reviews the completed file under the insurer's rules.
Accelerated underwriting
The insurer may skip the physical exam for an eligible applicant and use application answers, authorized external data, rules, and predictive models to reach or route a decision.
Simplified issue
The application uses fewer requirements and generally no fluids or physical exam. The NAIC notes that less information can be exchanged for generally higher premiums.
Guaranteed issue
The product uses eligibility rules instead of individual medical risk selection. Benefit amounts, waiting provisions, age limits, and prices can differ, so the policy wording matters.
Accelerated underwriting is not automatically better for a complex case. If the available data cannot answer the insurer's questions, the application may be routed to additional review.
Insurer, underwriter, agent and independent broker
These roles are connected, but they do not make the same decision. Licensing terms and legal duties can vary by state, so the descriptions below explain common U.S. usage rather than a rule for every jurisdiction.
Insurer
The insurance company issues the policy, accepts the contractual risk and is responsible for covered claims.
Underwriter
The person or team that examines and classifies the proposed risk under the insurer's rules. The underwriter does not sell the applicant an independent opinion.
Agent or producer
A licensed person who sells, services or negotiates insurance. An agent may represent one insurer, several insurers or work independently, depending on the arrangement and state terminology.
Independent broker
A licensed intermediary generally described as working for the customer and able to approach more than one insurer. The broker may still receive commission from the insurer that completes the sale.
THOUGH.you is an educational publisher, not any of these parties. Verify a company or producer through the appropriate state insurance department before relying on a sales or licensing claim.
Records and data an insurer may check
Evidence should answer a real question. More paperwork is not always better. The exact sources depend on the application, the insurer, the review route, consent, and applicable law.
| Evidence | What it can show | Simple example |
|---|---|---|
| Application answer | The applicant's statement | A diagnosis date or job duty |
| Exam, lab, or clinician record | A current measurement or dated medical pattern | Blood pressure readings, A1C results, or a follow-up note |
| Prescription or motor-vehicle data | Information that may confirm or question an application answer | A medication history or reported driving event |
| Authorized MIB consumer report | Coded underwriting information reported by participating member insurers | A flag that requires the insurer to investigate a possible mismatch |
| Specialist questionnaire | Details that a broad form cannot capture | Aircraft hours, climbing height or treatment stage |
| Activity or work record | A dated exposure pattern | A dive log, flight record, duty split, or safety certificate |
Medical underwriting and financial underwriting answer different questions
Medical and lifestyle review
This review considers mortality-related information such as health history, tobacco or substance use, driving, work duties, hazardous activities, and travel.
Financial review
This review considers the purpose and amount of coverage, income, assets, debts, existing insurance, pending applications, ownership, and the financial relationship between the parties.
A financially justified coverage request does not erase a medical or activity concern, and a strong health profile does not by itself justify any requested amount. Larger or unusual requests may need additional documentation.
Risk classes, ratings, extra charges, and other outcomes
Regular risk class
The application fits one of the insurer's available standard or preferred groups. Names and qualification rules vary.
Table or substandard rating
The insurer offers coverage using a higher mortality classification, which increases the premium under that product's pricing.
Flat extra charge
The insurer adds a stated charge for an identified risk. It may be temporary or permanent and may be used for an occupation or activity.
Offer with changed terms
A policy may limit a named activity where local rules allow it. Read the wording closely.
Postpone
The insurer does not make a current offer and may invite a later application after a clearer period or completed follow-up.
Decline
The insurer decides that the application falls outside its current rules. Another insurer may use different rules, but no alternative outcome is guaranteed.
Different insurers can reach different outcomes because their products and risk rules differ. No public checklist can promise a result.
What makes a case need more detail?
A broad label can hide the facts that drive a decision. Use the guide that matches the main source of extra questions:
- Health-condition underwriting often focuses on timing, treatment, control, follow-up and complications.
- Occupation underwriting often focuses on actual duties, location, equipment, travel and safety controls.
- Hobby and travel underwriting often focuses on frequency, limits, training, destinations and future plans.
Use the complete guide library when more than one part of an application may need supporting detail.
How to prepare a clearer application
Use dates and numbers
“March 2026” is clearer than “a while ago.” “Twenty dives a year” is clearer than “often.”
Separate current facts from future plans
Say what is true now and what you already expect to change.
Explain a mismatch
If two records appear different, add the short timeline that connects them.
Read the final application
Check that the submitted answers are complete and match what you intended to say.
Can a later job, trip or hobby affect an existing policy?
A later change does not usually reopen underwriting on a life-insurance policy that has already been issued. The policy is a contract, however, so the actual wording and applicable state law control. Do not assume that a general article overrides either one.
A new review may matter when the policy contains a relevant rider or condition, when the owner requests more coverage, reinstatement, replacement or another change that requires evidence of insurability, or when the concern is an inaccurate answer about facts that already existed during the original application. A new occupation, international itinerary or hazardous hobby can also affect a separate application for additional coverage even if the existing policy stays unchanged.
Read the issued policy and ask the insurer, servicing producer or a qualified adviser to answer in writing if the effect is unclear.
How to correct an inaccurate submitted answer
Contact the insurer or the licensed producer promptly instead of waiting for the application to finish. The insurer decides how the correction affects an application or issued policy.
- Identify the application, the exact question and the answer that needs correction.
- Give the complete corrected facts in writing. Do not alter an original document or ask someone to conceal the earlier answer.
- Ask whether a signed amendment, replacement page or other form is required.
- Keep the correction, delivery confirmation and the insurer's written response with the policy records.
- If the response is unclear or disputed, contact the insurance department in the state where the policy was purchased.
Do not send an application, policy number or medical record to THOUGH.you. We cannot change an insurer's file.
Primary sources for underwriting and consumer help
- National Association of Insurance Commissioners: Glossary of Insurance Terms
- National Association of Insurance Commissioners: Accelerated Underwriting
- National Association of Insurance Commissioners: Life Insurance consumer guidance
- MIB: Facts about applicant-authorized information exchange
- Consumer Financial Protection Bureau: MIB consumer reports and disputes
- New York Department of Financial Services: Life insurance terms, ratings, and underwriting
- National Association of Insurance Commissioners: How a state insurance department can help
Common questions about life-insurance underwriting
What does a life-insurance underwriter do?
An underwriter reviews the application and evidence. The underwriter compares the risk with the insurer's rules and decides which terms the insurer can offer.
How long does life-insurance underwriting take?
Timing varies. A simple digital review may be quick. A case that needs medical records, financial evidence or a specialist questionnaire can take longer.
Can an applicant improve an underwriting decision?
You cannot control an insurer's rules. Complete and consistent facts can still prevent avoidable delays and overly cautious assumptions.